First home buyers in Queensland and Victoria: you might be closer to owning than anyone's told you.
The federal 5% Deposit Scheme has had no income cap since 1 October 2025, and Queensland and Victoria each offer grants and stamp duty concessions to eligible buyers. A free 5-minute call talks through which options may suit you, and what to check next.


their first home
How can a first home buyer buy with a 5% deposit?
Under the Australian Government 5% Deposit Scheme, eligible first home buyers can purchase with a 5% deposit (2% for eligible single parents and legal guardians) and avoid lenders mortgage insurance. It is a government guarantee on part of the loan, not a grant or a loan approval, and since 1 October 2025 it has no income cap and no limit on places. Your Property Pathway helps you understand government home buyer schemes, grants and concessions in Queensland, Victoria and Western Australia, including how they work, published eligibility requirements and applicable property price caps. Home loan assistance is provided separately by My Finance People. The first 5-minute call is free.
Buying in Western Australia? See the WA first home buyer grants guide. Buying new? Read house and land packages for first home buyers.
Official sources and review date
Scheme facts checked: . This check covers the Australian Government 5% Deposit Scheme and property price caps, plus the Victorian and Queensland grant amounts, property-value limits and duty summaries on this page. Eligibility rules apply; check the official guidance before making a decision.
- Australian Government 5% Deposit Scheme
- Scheme eligibility and frequently asked questions
- Scheme property price caps
- Victoria: First Home Owner Grant
- Victoria: first home buyer duty exemption or concession
- Queensland: First Home Owner Grant eligibility
- Queensland: first home (new home) duty concession
Before you buy: a first home buyer checklist
- Choose your state, and new or established. The First Home Owner Grant is for new homes only, and stamp duty rules differ between a completed home and land with a separate build. Start with the Queensland or Victorian guide.
- Ask a licensed finance provider about borrowing. How much you can borrow, and whether the repayments are affordable for you, is assessed by a licensed finance provider, such as My Finance People or your chosen lender.
- Check each scheme separately. The grant, the stamp duty concession and the 5% Deposit Scheme each have their own administrator and criteria. Qualifying for one doesn't mean you qualify for the others, and a price under a cap doesn't on its own make you eligible.
- Get the total cost and contract advice before you commit. Get the full price in writing, including build inclusions and site costs on a new build, and have a solicitor or conveyancer review the contract before you sign. The house and land checklist covers what to ask.
Planning to put a grant towards your purchase? Read can you use the First Home Owner Grant as a deposit? to see when it is paid in Victoria and Queensland.
Working out what you need beyond the deposit? See our guide to the upfront costs of buying your first home.
First, the number nobody wants to add up
$600 a week. Times 52. Times five years.
Go on, punch it into the calculator. We'll wait.
That's $156,000.
That's five years of rent at $600 a week. It isn't wasted, because it pays for a home to live in, but it's a big number, and it's worth knowing whether owning could be an option for you.
Owning doesn't simply redirect that money into your own pocket, though. A mortgage repayment is partly interest, and owners also pay council rates, insurance, maintenance and, for some homes, body corporate or owners corporation fees. Equity builds as you pay down the loan, and depends on what the home is worth.
The reason you're still renting might not be the one you think
You've probably been told you need a 20% deposit. Save the 20%, then you're allowed to buy.
Here's the thing. Nobody ever actually wrote that rule down. Not the banks. Not the government. Nobody.
It just feels true. So families sit on leases for years, saving toward a number nobody actually requires, watching prices move faster than the savings account ever could.
For some renters it genuinely isn't the right time. For others, nobody has ever sat down with them and looked at what might be possible.
“I can't afford to buy” and “I've never actually checked” are two very different sentences. One of them takes five minutes to start on.
There's a federal government scheme many renters haven't heard of
It's not a grant. It's not a “hack.” It's a real, current scheme, and since 1 October 2025 it has had no income cap, though a lender still has to approve your loan.
“So why haven't I heard of it?”
Fair question. It never made the front page. And it's not the kind of thing a landlord brings up over the lease renewal.
Its official name is the Australian Government 5% Deposit Scheme (you might have heard it called the First Home Guarantee). Eligible first home buyers can buy with a 5% deposit and skip lenders mortgage insurance. It's a government guarantee on part of the loan, not a grant and not a loan approval.
Whether it fits you comes down to three separate checks.
Read the full breakdown: QLD first home buyer grants in 2026 →
Read the full breakdown: VIC first home buyer grants in 2026 →
What the first call covers
- How the schemes work, and which may suit you. We help you understand government home buyer schemes, grants and concessions, including how they work, published eligibility requirements and applicable property price caps. Final eligibility is determined by the relevant government authority, scheme administrator or participating lender. Home loan advice and credit assistance are provided separately by My Finance People or your chosen finance provider.
- Who assesses your borrowing. How much you can borrow, and whether the repayments are affordable, is assessed by a licensed finance provider: My Finance People, or your chosen lender. The call doesn't assess or approve a loan.
- A realistic next step. Whether it makes sense to start now, and what to check first.
- If the timing isn't right yet, the things worth working on. A plan beats a maybe.
Home loan and credit assistance services are provided by My Finance People Pty Ltd (ACN 169 314 881), Credit Representative No. 462071, operating under Australian Credit Licence 389328. Your Property Pathway and My Finance People are separate businesses. Your Property Pathway does not provide credit assistance and receives no commission or referral fee from finance providers.
No documents. No credit check. Nothing touches your credit file. No obligation.The worst it can cost you is five minutes.
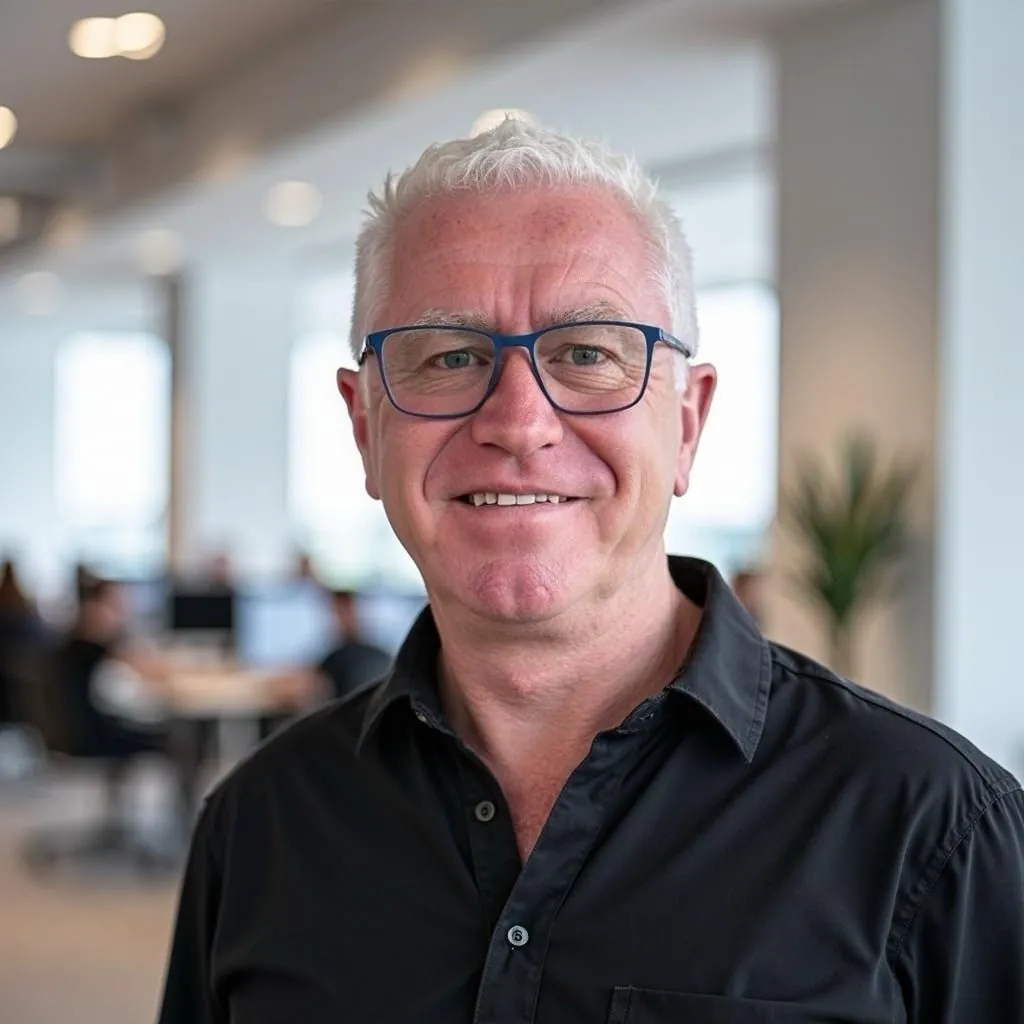
Clive has spent three decades in new homes. House and land packages. First home buyers. The lot. Thirty years, and one thing never changed: the renters.
Every year he'd meet hundreds of them. Steady jobs. Decent incomes. Paying off a home week after week. Just never their own. After thousands of those conversations, he knew something they didn't. More often than people expected, owning was closer than they'd assumed.
So getting renters out of renting became the whole job. Today, more than 1,000 families are in first homes of their own because of it. The reviews call him “down-to-earth” and “these are your guys.”
Renters who stopped guessing and started owning
“I'm impressed with Clive's experience and real support in helping me purchase a new house and land property. He genuinely wants clients to achieve their goals — always available for my questions, and quick to respond. Bloody legend, mate!”
Is this call worth five minutes of your time?
Book the call if...
- You're renting and wondering whether owning could be an option.
- You've got a steady income but assume owning is out of reach.
- You've never had anyone walk you through what might be possible.
Probably skip it if...
- You're happy renting and not fussed about owning a place.
- You're after a pushy sales pitch or a magic bean. You won't get either here.
- You'd rather keep guessing than hear a straight answer.
Talk through your options. Free, in five minutes.
A few quick details, then pick a time that suits. One of Clive's team calls to talk through your options and next steps. Borrowing is assessed separately by a licensed finance provider.
Worst case, you hear an honest “not yet” and what to work on. Best case, you leave with a clear next step.
Prefer to talk now? Call 0418 252 432.
Fair questions
What is the federal first home scheme you keep mentioning?
It's the Australian Government 5% Deposit Scheme, formerly known as the First Home Guarantee and the Home Guarantee Scheme, run by Housing Australia through participating lenders. Eligible first home buyers can purchase with a minimum 5% deposit (2% for eligible single parents and legal guardians), and because the government guarantees part of the loan, they avoid paying lenders mortgage insurance. It is a guarantee, not a grant or a loan approval: a participating lender still assesses your application. Since 1 October 2025 there is no income cap and no limit on places.
How much deposit do I need to buy my first home?
If you are eligible, often less than the 20% many people assume. Under the 5% Deposit Scheme, an eligible buyer can purchase with a 5% deposit (2% for eligible single parents and legal guardians) if a participating lender approves the loan: $35,000 on a $700,000 home, with no lenders mortgage insurance. Grants are separate: an eligible buyer of a new home may get $30,000 in Queensland (home including land valued below $750,000) or $10,000 in Victoria ($750,000 or less). Don't count on a grant as part of your deposit, because of when it is paid (see Queensland and Victoria).
What are the 5% Deposit Scheme price caps in QLD, VIC and WA?
Queensland: $1,000,000 in Brisbane, the Gold Coast and the Sunshine Coast, and $700,000 in the rest of the state. Victoria: $950,000 in Melbourne and Geelong, and $650,000 elsewhere. Western Australia: $850,000 in Perth, and $600,000 elsewhere. Caps are set by postcode, and both the price and the lender's valuation must sit at or below the cap. Queensland, Victorian and Western Australian property price caps checked against the official scheme guidance on 4 November 2026.
Is this a sales call?
No. It's a 5-minute conversation about your options, nobody pitches you on this call, and you get your answers to keep, either way. Your Property Pathway does not charge you any service fees throughout the entire process. We receive no commission or referral fees from any finance providers, land developers, or legal companies. Our remuneration comes from the wholesaler upon successful construction.
Will it affect my credit score?
No. No credit check, no paperwork, nothing touches your credit file. It's a conversation, not an application.
I don't think I earn enough, or I've got no deposit.
Income still matters: the 5% Deposit Scheme has had no income cap since 1 October 2025, but a lender assesses what you can borrow and repay. Most options also need some deposit: 5% under the 5% Deposit Scheme, or 2% for eligible single parents and legal guardians. The team can talk through which options may suit you, and a licensed finance provider assesses the lending side.
Why does a private company know about a government scheme?
Because walking renters through that door is the whole reason Your Property Pathway exists. The scheme doesn't advertise itself. We do.
What if I don't qualify?
Then we'll say so, and talk through what might change that, such as a different price range, location, deposit or timing. Final eligibility is decided by each scheme's administrator or lender, not on the call.
How long is the call, really?
About five minutes. No documents to dig up. A few questions, and an honest first view of your options.
Not a first home buyer? We also help investors build a property portfolio across QLD, VIC and WA, and can point existing owners to My Finance People for a home loan review. Or meet the team who'd be doing the checking.
Renting or buying, it pays to know your options
Five minutes is enough to understand what might be possible, and what to check next.
In late 2025 the scheme was expanded — the yearly cap on places was scrapped, and it now covers more incomes and higher-priced homes than before. It may fit you even if it didn't a year ago. Five minutes now beats hearing about it at a barbecue in two years.
P.S. Two sentences worth remembering. “I can't afford to buy” and “I've never actually checked” are not the same thing. One of them takes five minutes to start on, and it costs you nothing.